Premium vs
No Annual Fee
Credit Cards
Is a Premium Card Worth the Fee?
Compare Capital One Venture X and Wells Fargo Active Cash to see how a premium card stacks up against a no annual fee card in rewards, benefits, and overall value.
Search Articles

Choosing a credit card is not just about finding the highest rewards rate or the biggest welcome offer. The right card should match your spending habits, lifestyle, and the benefits you are likely to use throughout the year.
Premium credit cards often come with travel perks, airport lounge access, welcome bonuses, and additional protections. However, these benefits usually come with an annual fee. No annual fee cards, on the other hand, offer a simpler way to earn rewards without paying a recurring fee just to keep the card.
In this guide, we compare Capital One Venture X and Wells Fargo Active Cash to explore how premium and no annual fee cards differ. We will look at rewards, fees, travel benefits, redemption options, and everyday value to help you decide which type of card makes more sense for you.
Table of Contents
What to Consider When Comparing Premium and No Annual Fee Credit Cards

Different Card Types
See how premium and no-annual-fee cards compare.
Find Your Perfect Fit
Look beyond the annual fee and check total benefits.

Key Features Side by Side
Compare rewards, perks, fees, and more.
Compare Total Card Value
Choose the card that matches your lifestyle and goals.
Related Articles
Subscribe for Updates
Get the latest credit card guides, tips and offers straight to your
No spam, Unsubscribe anytime
Choosing between a premium credit card and a no annual fee card requires more than comparing their yearly costs. Both types can offer useful rewards, but their value depends on how you spend, how often you travel, and which benefits you actually use.
A premium card may include travel credits, airport lounge access, purchase protection, and additional rewards. A no annual fee card may offer fewer extras but can still provide excellent value without adding a recurring cost.
Before making a decision, consider the following factors to understand which type of card is more suitable for your needs.
Different Card Types
Credit cards come with different reward structures and benefit packages. Premium cards are often designed for people who want additional travel benefits, exclusive services, and enhanced rewards. No annual fee cards generally focus on keeping rewards simple and avoiding yearly ownership costs.
Some cards offer cashback on everyday purchases, while others provide points or miles that can be redeemed for travel, gift cards, or other eligible rewards.
Understanding these differences is the first step toward choosing a card that matches your spending habits.
Find Your Perfect Fit
The right credit card should fit naturally into your lifestyle. If you travel frequently, you may find value in airport lounge access, travel credits, and other premium benefits. If most of your spending goes toward groceries, shopping, dining, and household expenses, a straightforward cashback card may be more practical.
Think about how you normally use your credit card instead of choosing one simply because it offers more features. A card that matches your everyday needs can provide better long-term value than one with benefits you rarely use.
Key Features Side by Side
Comparing important features side by side can make your decision much easier. Look at the rewards rate, annual fee, welcome bonus, redemption options, foreign transaction fees, and additional benefits.
Also check the conditions attached to each feature. Some rewards apply only to selected spending categories, while certain credits or travel benefits may require activation or qualifying purchases.
A detailed comparison helps you understand what each card offers and what you may have to pay to access those benefits.
Find the Right Fit
Once you have compared the rewards, fees, and benefits, consider which card offers the most practical value for your situation.
A premium card may be a suitable choice if you regularly use its travel benefits and can justify the annual fee. A no annual fee card may be a better option if you prefer simple rewards and want to avoid recurring costs.
There is no universal winner. The best choice is the card that supports your spending habits, provides benefits you can actually use, and fits comfortably within your budget.
Before applying, review the latest terms, fees, eligibility requirements, and reward conditions on the card issuer’s official website.
Premium vs No Annual Fee Credit Cards: Detailed Comparison
See how Capital One Venture X and Wells Fargo Active Cash stack up across key features.
Feature
Capital One Venture X
American Express Gold Card
Rewards Type
Travel Rewards (Capital One Miles)
Cashback
Rewards Rate
10x on hotels & rental cars (Capital One Travel), 5x on flights (Capital One Travel), 2x on all other purchases
2% unlimited cashback on all purchases
Annual Fee
$395
$0
Welcome Bonus
75,000 bonus miles (after spending $4,000 in the first 3 months)
$200 cashback (after spending $500 in the first 3 months)
Best For
Frequent travelers, premium benefits, lounge access
Everyday spending, simplicity, no annual fee
Redemption Options
Travel, statement credit, transfer to partners
Statement credit, direct deposit, check, gift cards
Foreign Transaction Fee
0%
3%
Card Network
Visa
Visa
Additional Perks
Airport lounge access, travel credits, Global Entry/TSA credit, travel insurance, premium travel benefits
Cell phone protection, purchase protection, no annual fee, easy to use rewards
A side-by-side comparison makes it easier to understand what you actually receive from a credit card. Instead of focusing only on the rewards rate, consider the annual fee, welcome bonus, redemption flexibility, and additional benefits.
Premium cards are generally designed for people who can take advantage of travel-related perks and higher-value rewards. No annual fee cards are often more suitable for people who prefer straightforward rewards and want to avoid an ongoing card cost.
When comparing two cards, look beyond the advertised benefits. A premium card may offer valuable extras, but those benefits only matter if you use them. Similarly, a no annual fee card may offer fewer premium features while still providing excellent value for everyday purchases.
Rewards Type
Rewards programs can work differently depending on the card. Some cards earn travel miles or flexible points, while others provide cashback on eligible purchases.
Travel rewards can be useful if you regularly book flights, hotels, or other travel services. Cashback is generally easier to understand because the reward has a direct monetary value.
Think about how you prefer to use your rewards before choosing a card.
Rewards Rate
The rewards rate tells you how much value you can earn from eligible spending. Some cards offer a flat rewards rate, while others provide higher rewards on selected purchases or spending categories.
A higher advertised rate does not automatically mean a better card. Check which purchases qualify, whether spending caps apply, and how rewards can be redeemed.
Annual Fee
The annual fee is one of the biggest differences between premium and no annual fee credit cards.
A premium card may charge a significant yearly fee in exchange for travel benefits, statement credits, lounge access, or other perks. A no annual fee card avoids this recurring cost, making it easier to keep the card for long-term everyday use.
Before paying an annual fee, estimate the value of the benefits you will realistically use. Do not count benefits that you would not normally purchase or use.
Welcome Bonus
Welcome bonuses can provide a valuable boost when opening a new credit card. Depending on the card, the offer may include bonus miles, points, or cashback after meeting a minimum spending requirement within a specified period.
Always check the spending requirement and deadline. A welcome bonus is only worthwhile if you can meet the requirement through normal spending without buying things you do not need.
Best For
Premium cards may be a better fit for frequent travelers who can use airport lounge access, travel credits, insurance benefits, and other premium features.
No annual fee cards may suit people who want simple rewards, predictable value, and no yearly card fee.
Your spending habits and lifestyle should guide the decision rather than the card’s marketing label.
Redemption Options
Redemption flexibility is another important factor. Depending on the rewards program, you may be able to use rewards for travel bookings, statement credits, gift cards, or transfers to participating travel partners.
Some programs offer more value through specific redemption methods than others. Review the available options and understand whether restrictions, minimum redemption amounts, or other conditions apply.
Foreign Transaction Fee
If you regularly travel internationally or shop from overseas websites, foreign transaction fees can affect the overall value of a credit card.
Some cards charge a fee on eligible transactions made in a foreign currency, while others do not. Check the card’s current pricing and terms before using it abroad.
Card Network
The card network determines where your card is accepted and may provide certain network-level benefits.
Visa and Mastercard are widely accepted in many countries, but acceptance can still vary by merchant and location. Check the network and any additional benefits that come with the specific card.
Additional Perks
Premium credit cards may include benefits such as airport lounge access, travel insurance, purchase protection, rental car coverage, or statement credits.
No annual fee cards may offer fewer premium extras, but they can still provide useful features for everyday spending.
Compare the actual terms of each benefit. Some perks require enrollment, have usage limits, or apply only to qualifying purchases.
Pros and Cons
A quick look at what each card does well and where it may not be the best fit.
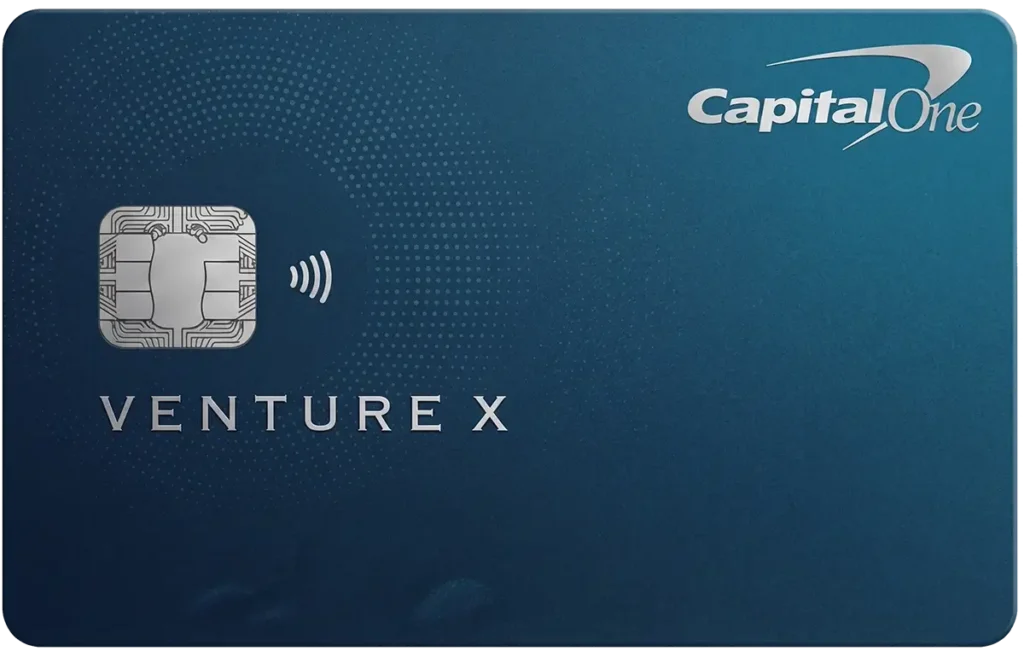
Capital One Venture X
Pros
High rewards on travel and everyday spending
Airport lounge access (Priority Pass)
Valuable welcome bonus
Travel credits and premium perks
Cons
$395 annual fee
Best value for frequent travelers
More complex rewards system
May offer more perks than casual users need

Wells Fargo Active Cash
Pros
2% unlimited cashback
No annual fee
Simple and easy to use
Great for everyday spending
Cons
No travel rewards
3% foreign transaction fee
Fewer premium perks
Not ideal for frequent travelers seeking premium benefits
Every credit card has advantages and limitations. The best way to compare premium and no annual fee cards is to consider both sides rather than focusing only on their rewards.
Capital One Venture X – Pros
Potentially valuable travel rewards.
Airport lounge access at eligible locations.
Travel-related credits and benefits.
Welcome bonus opportunities for eligible applicants.
Useful features for people who travel regularly.
Capital One Venture X – Cons
Charges an annual fee.
Premium benefits may not suit occasional travelers.
Some rewards require understanding the redemption program.
Certain benefits may have conditions or eligibility requirements.
The card may offer less value if you rarely use its travel features.
Wells Fargo Active Cash – Pros
No annual fee.
Straightforward cashback structure.
Easy-to-understand rewards on eligible purchases.
Suitable for everyday spending.
No need to manage complicated travel redemption options.
Wells Fargo Active Cash – Cons
Does not offer the same range of premium travel benefits.
No airport lounge access as a standard card benefit.
May not be the best fit for people seeking travel-specific rewards.
Foreign transaction fees may apply.
Fewer premium perks than high-end travel cards.
Who Should Choose Which Card?
Your spending habits and lifestyle can help you decide.
Choose Capital One Venture X If...
You travel frequently and want premium benefits
You want airport lounge access
You can take advantage of travel credits
You don’t mind paying an annual fee for extra perks
Choose American Express Gold Card If...

You want simple, unlimited cashback
You don’t want to pay an annual fee
You mainly spend on everyday purchases
You prefer flexibility and easy redemptions
There is no single credit card that works best for everyone. The right choice depends on how frequently you travel, how much you spend, and whether you will use the benefits included with the card.
Choose Capital One Venture X If…
A premium travel card may be worth considering if you:
Travel frequently and want travel-related rewards.
Can take advantage of airport lounge access.
Value travel credits and additional card benefits.
Prefer earning rewards that can be used for travel.
Are comfortable paying an annual fee when the benefits justify the cost.
Choose Wells Fargo Active Cash If…
A no annual fee cashback card may be a better fit if you:
Prefer simple and predictable cashback.
Want to avoid paying an annual fee.
Mainly use your card for everyday purchases.
Do not need premium travel benefits.
Prefer straightforward rewards instead of managing a travel points program.
Before applying, review the latest card terms, eligibility requirements, fees, and reward conditions on the issuer’s official website.
For more information about credit cards and how they work, visit the Consumer Financial Protection Bureau’s credit card resources.
Frequently Asked Questions
Is a premium credit card worth the annual fee?
A premium credit card can be worth the annual fee if you regularly use its travel credits, airport lounge access, rewards, insurance, and other benefits. It may not be worthwhile if you rarely use these perks or do not spend enough to justify the fee.
How does Capital One Venture X compare to Wells Fargo Active Cash?
Capital One Venture X is designed for frequent travelers who want travel rewards, lounge access, and premium benefits. Wells Fargo Active Cash focuses on simple, unlimited cashback with no annual fee, making it more suitable for everyday spending.
Which card is better for everyday spending?
Wells Fargo Active Cash may be more convenient for everyday spending because it offers simple, unlimited cashback and has no annual fee. Capital One Venture X may provide more value when spending is focused on travel and premium rewards.
Can I use Capital One miles for international travel?
Yes, Capital One miles can generally be redeemed for travel, including international flights and hotels. Depending on the redemption method, miles may also be transferred to eligible travel partners for potentially greater value.
Which card gives more long-term value?
Long-term value depends on your spending habits and how frequently you use the card’s benefits. Capital One Venture X may provide greater value to frequent travelers who use its premium perks, while Wells Fargo Active Cash can offer consistent value through unlimited cashback without an annual fee.
Compare. Decide. Earn More.
Explore more credit card comparisons and find the best card for your lifestyle.